Features
Built around what's coming, not just what happened.
Dimewell plans from payday to payday. Every bill, debt and transaction feeds one number: what's left after bills, counting only money that has posted.
The Financial Pulse, explained
- 1
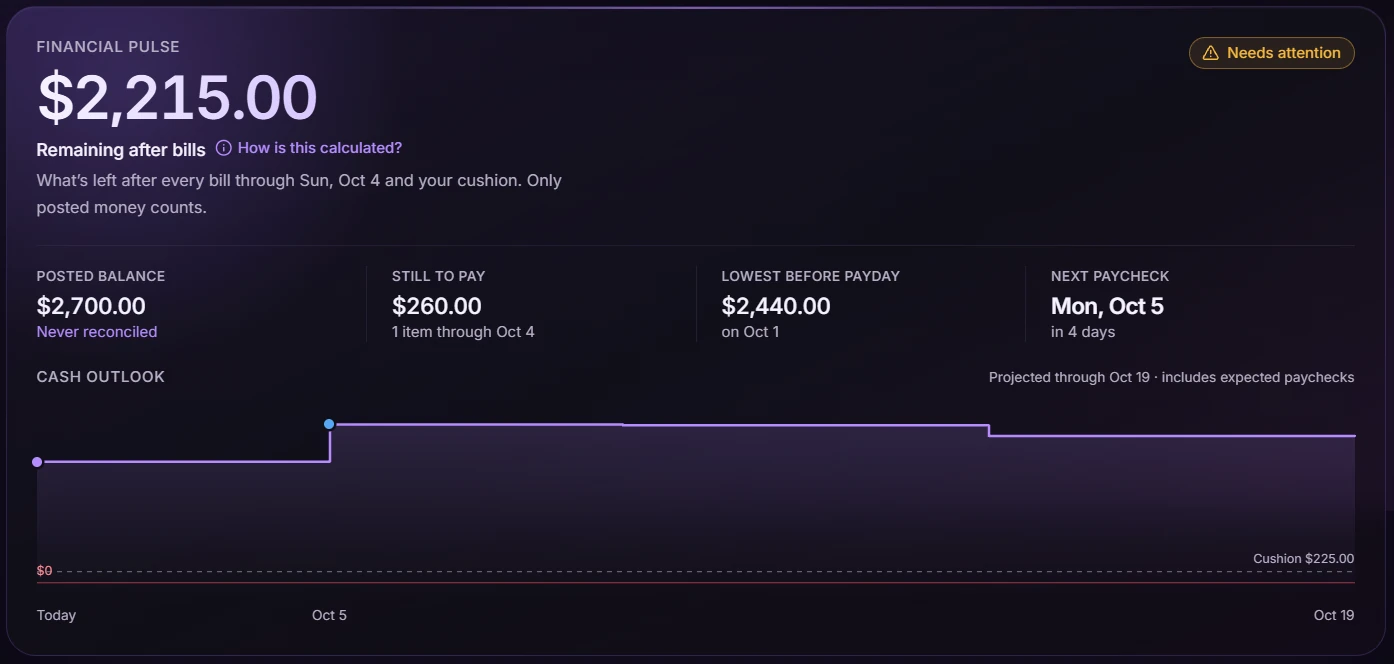
Remaining after bills
What's left after every bill before payday and your cushion. Only posted money counts.
- 2
One-line status
On track, cushion getting low, short on a date, or needs attention. Worked out by stated rules, never a score.
- 3
Four figures
Posted balance, still to pay, the lowest point before payday, and when the next paycheck lands.
- 4
Cash outlook
Your projected balance day by day through the next paycheck period, with your cushion as a dashed line.
Financial Pulse · fictional demo data
The planner
Six parts, one picture of the next few days.
Bills
Bills that know when they're due.
Add each bill once: how much, how often, and whether you pay it by hand or it drafts automatically. Dimewell lays every due date into the paycheck period it falls in, and sets aside whatever is still to pay before your next payday.
Record a payment against the bill and it stops being reserved. Paid part of it? Only what's left stays set aside, so a payment is never counted twice.
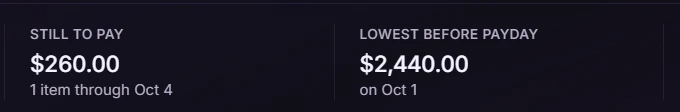
Dashboard · still to pay before payday
Debts
Debts with a balance you can trust.
Keep credit cards, buy-now-pay-later plans and loans in one place. When the bill that pays a debt is linked to it, every recorded payment lowers the balance automatically.
Check the balance against your statement now and then. Dimewell shows the difference, usually interest, and adds it as a dated entry once you confirm. Nothing you logged earlier is rewritten.
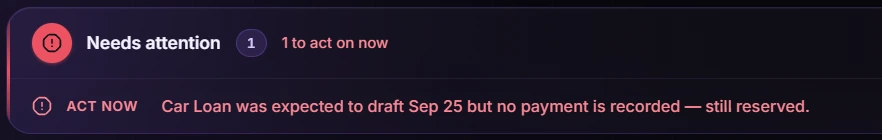
Dashboard · a loan draft that hasn't been recorded
Transactions
A ledger that only counts what posted.
Paychecks, bill payments, transfers and adjustments each take a few seconds to record. Every account keeps its own running balance, and you can search, filter and export to CSV.
Pending money is shown but never counted. Once you reconcile with your bank, the history up to that date is protected, and any change to it asks you first.
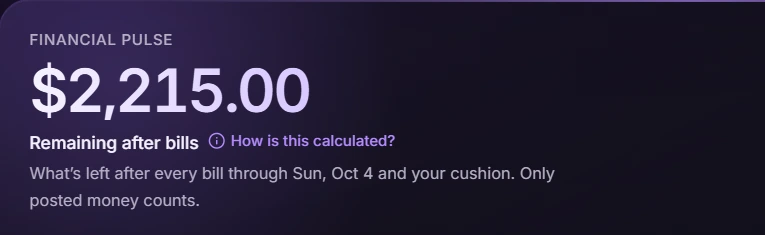
Dashboard · only posted money counts
Forecasting
A forecast that's labelled as one.
The cash outlook walks your balance forward day by day through the next paycheck period, including the paychecks you expect. It marks paydays and your lowest point, and shows your cushion as a line you can see coming.
Expected paychecks are always marked as projected. They shape the forecast, never the number you can spend today.
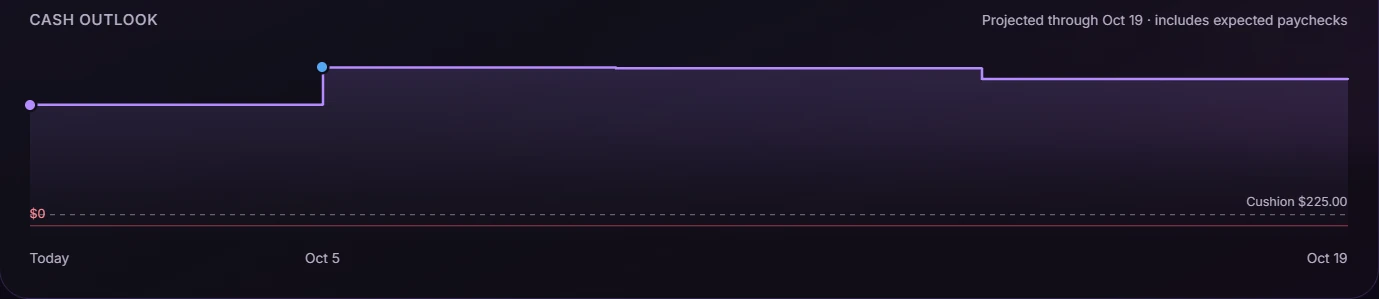
Dashboard · cash outlook
Alerts
The things that need you, first.
Needs attention collects anything that needs you: an overdue bill, a draft that hasn't shown up, a shortage coming before payday. Each item is tagged Act now, Check or Note, most urgent first.
When there's nothing to act on, the section simply isn't there.
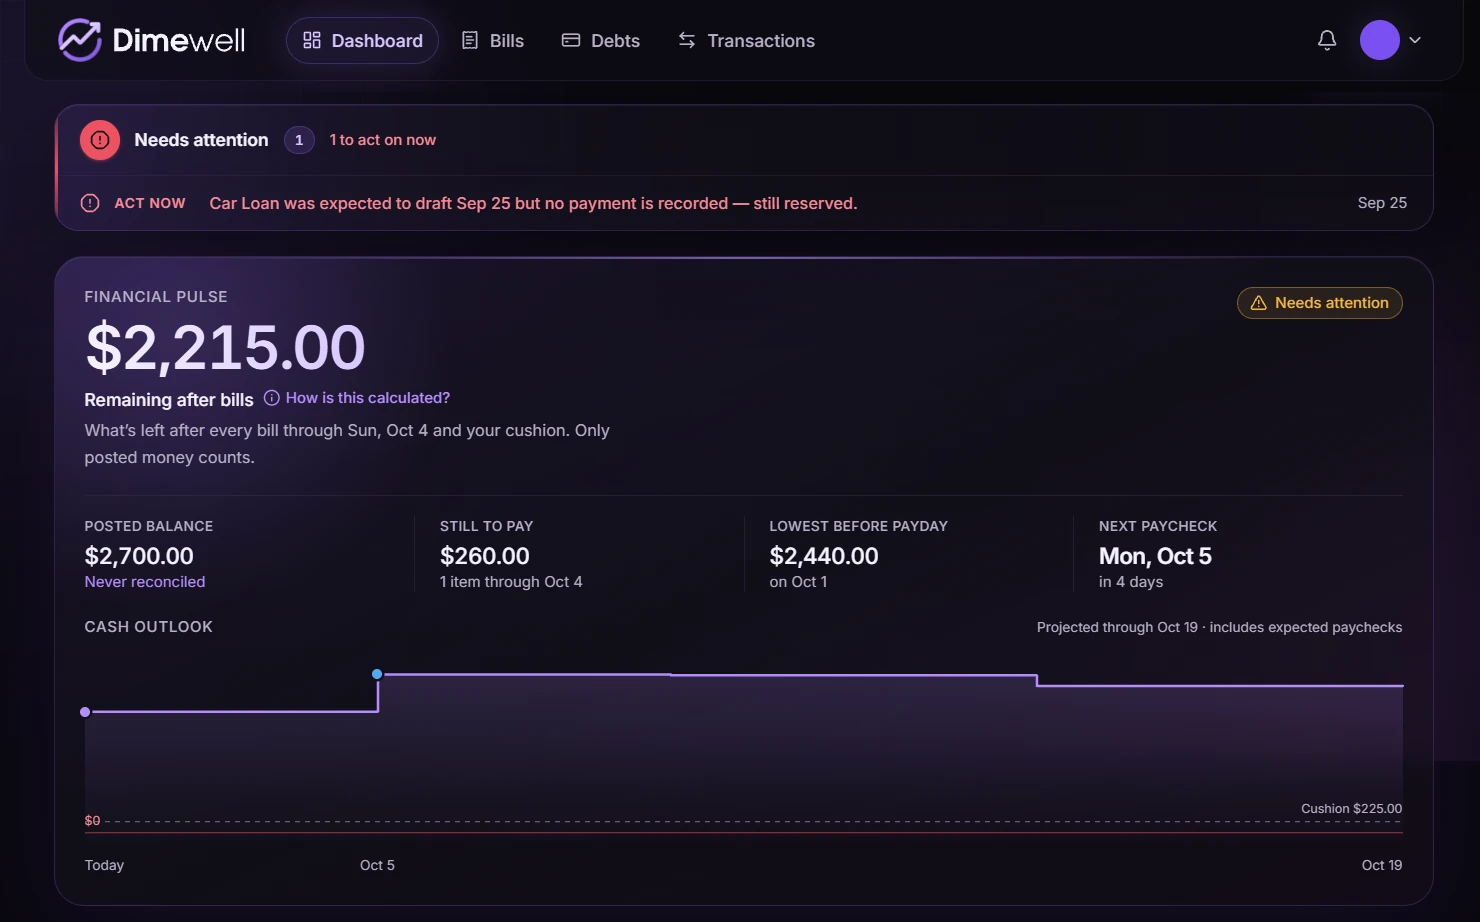
Dashboard · needs attention sits at the top
Every device
Start on your laptop. Check it on your phone.
Dimewell runs in the browser and as apps for iPhone and Android. Sign in anywhere and it's the same account, the same bills, the same plan.
On your phone you can lock the app with Face ID or your fingerprint, a setting for that phone only.
- Web
- iPhone
- Android
One account · one plan
How Dimewell thinks about your money
Your balance isn't what you have to spend.
Your bank shows what has posted. It doesn't know about the rent due Friday or the card payment drafting on the 3rd. Spend from that number and the bills arrive anyway.
Dimewell starts from the same posted balance, then takes off every bill due before your next paycheck and the cushion you choose to keep. It checks the balance day by day and plans around the lowest point. Money that hasn't posted, like tomorrow's paycheck, is never counted.
Dimewell is a planning tool. It doesn't move money or give financial advice, and it never connects to your bank: you record what happens, and it shows you where that leaves you.
- Posted balance
- $2,700.00
- Bills still to pay before payday
- −$260.00
- Your cushion
- −$225.00
- Remaining after bills
- $2,215.00
Next paycheck, Mon, Oct 5: expected, not counted.